
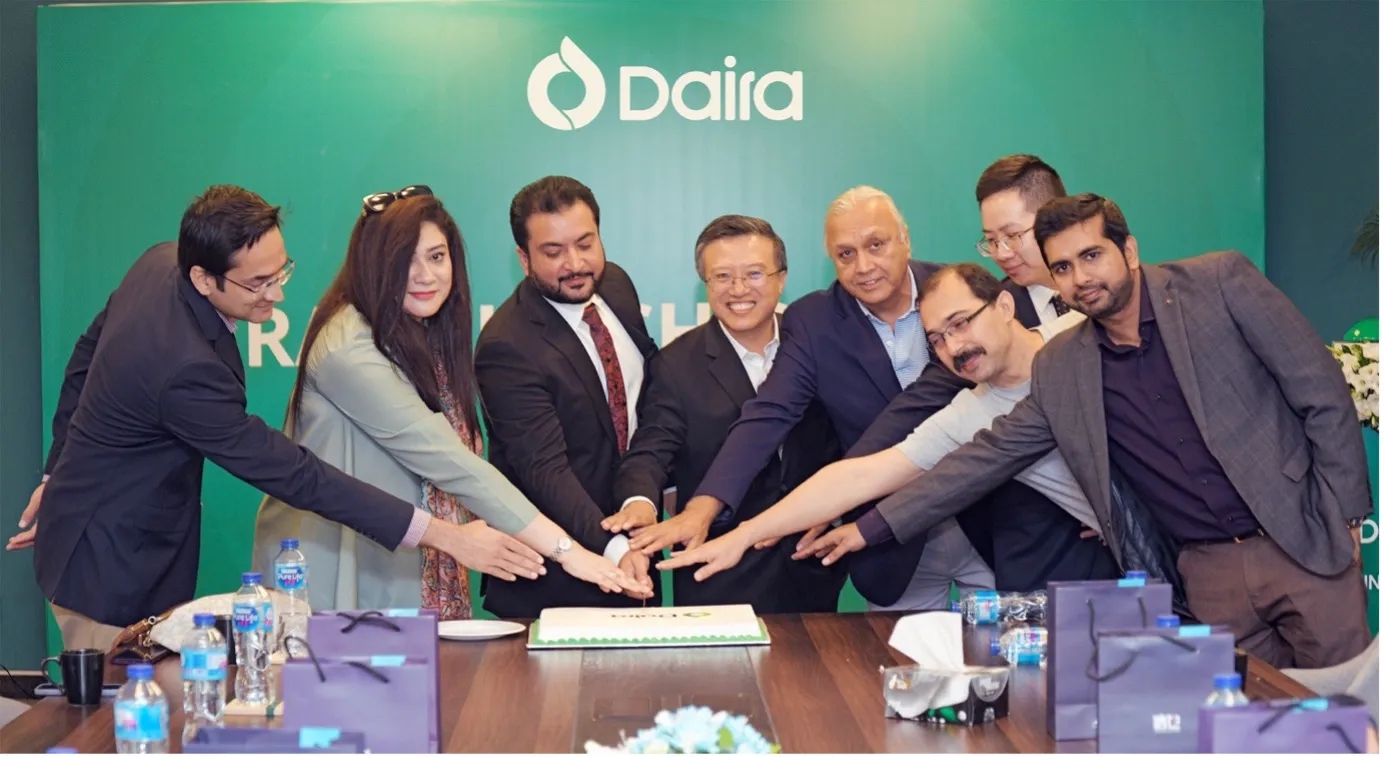
Pakistan’s digital payments sector has experienced a significant transformation in 2025 with the entry of several Chinese fintech firms, signaling a deepening of China-Pakistan economic and technological collaboration. Companies including Ant Group, Tencent, and JD Finance have begun operations in Pakistan, offering digital wallets, online payment gateways, and AI-powered financial services tailored to local consumers and businesses. According to the State Bank of Pakistan (SBP), digital transaction volumes increased by 28% in the first half of 2025, reaching 15 billion PKR, highlighting strong market adoption.
The entry of Chinese fintech players aligns with Pakistan’s broader strategy under the “Digital Pakistan” initiative, aiming to enhance financial inclusion, modernize payment infrastructure, and integrate advanced financial technologies into commercial and retail ecosystems. Analysts suggest that these developments could accelerate e-commerce growth, support small and medium enterprises (SMEs), and position Pakistan as a regional hub for fintech innovation.
Market Entry and Regulatory Framework
The Pakistani government and the SBP have facilitated Chinese fintech entry through clear regulatory frameworks, licensing procedures, and cross-border investment agreements. Digital wallets and mobile payment platforms require licensing under SBP’s Payment Systems and Electronic Fund Transfer Act, ensuring security, compliance, and consumer protection.
To encourage innovation, SBP has introduced sandbox environments for fintech startups and foreign firms, allowing pilot testing of payment solutions, AI-driven lending, and digital banking applications. “Our goal is to create a secure and innovative digital payments ecosystem, providing Pakistani consumers with modern financial services while ensuring compliance with international standards,” stated SBP Deputy Governor, Mr. Muhammad Ashraf.
Services Offered by Chinese Fintech Firms
Chinese fintech companies are introducing a wide range of digital financial services in Pakistan, including:
- Digital Wallets: Enabling peer-to-peer transfers, bill payments, and online purchases.
- AI-Powered Credit Scoring: Leveraging machine learning to assess creditworthiness for SMEs and individuals without traditional credit histories.
- Mobile Payment Gateways: Facilitating seamless online payments for e-commerce, ride-sharing, and utility services.
- Cross-Border Payment Solutions: Streamlining transactions between Pakistan and China, supporting trade settlements under CPEC projects.
- Blockchain-Enabled Platforms: Enhancing transparency, security, and traceability in digital transactions.
These services complement existing local providers such as Easypaisa and JazzCash, introducing competition that encourages innovation and service improvements. Early adoption metrics indicate strong consumer interest, particularly among urban millennials and small business owners seeking efficient and cost-effective payment solutions.
Impact on Financial Inclusion
The introduction of Chinese fintech services is expected to significantly enhance financial inclusion in Pakistan. According to the World Bank’s Global Findex database, approximately 35% of Pakistan’s adult population remains unbanked. Digital wallets and mobile payment platforms can bridge this gap by providing accessible financial services to rural populations, low-income households, and small enterprises.
Programs targeting microfinance, AI-assisted credit, and digital savings accounts are being piloted to provide previously excluded demographics with access to financial tools. Analysts estimate that by 2027, fintech adoption could expand to cover over 60% of Pakistan’s adult population, contributing to economic empowerment and reduced reliance on cash transactions.
Collaboration with Local Banks and Startups
Chinese fintech firms are partnering with Pakistani banks and startups to enhance service delivery. Joint initiatives include integrated digital payment systems, shared AI algorithms for fraud detection, and localized mobile applications. For example, Tencent has collaborated with several commercial banks to provide digital wallets linked to existing banking accounts, ensuring seamless transfers and bill payments.
Startups are also benefitting from technology transfer, training programs, and access to AI-based analytics tools, allowing them to compete more effectively in the domestic market. Industry experts note that these collaborations foster a knowledge-sharing ecosystem, where local fintech talent gains exposure to advanced technologies and global best practices.
Economic Implications
The entry of Chinese fintech firms contributes to economic growth by stimulating e-commerce, increasing efficiency in financial transactions, and supporting SMEs in scaling operations. Lower transaction costs, faster payments, and expanded access to credit enable businesses to operate more efficiently, particularly in export-oriented sectors linked to China under CPEC.
Additionally, the development of cross-border digital payment systems supports trade settlement between Pakistan and China, providing a secure and efficient mechanism for transactions in both goods and services. Analysts predict that improved digital financial infrastructure will reduce reliance on informal channels, mitigate currency risks, and enhance transparency in cross-border trade.
Challenges and Risk Mitigation
Despite promising opportunities, challenges exist in the fintech sector. Cybersecurity risks, data privacy concerns, and low digital literacy among certain population segments pose obstacles. The SBP and fintech firms are implementing multi-layered security measures, user education programs, and regulatory compliance frameworks to mitigate these risks.
Additionally, interoperability with local banking systems and legacy financial infrastructure remains a technical challenge. Collaborative pilot programs, sandbox testing, and phased deployment strategies are being employed to ensure seamless integration without disrupting existing financial services.
Job Creation and Skills Development
Chinese fintech investments are also generating employment opportunities in technology, customer support, data analytics, and financial services. Training programs for Pakistani engineers, developers, and financial analysts are an integral part of the market entry strategy. Over 1,000 jobs are expected to be created directly, with several thousand more in related sectors such as e-commerce, logistics, and digital marketing.
Future Outlook
The presence of Chinese fintech firms in Pakistan signals a transformative phase for the country’s digital payments ecosystem. Analysts forecast rapid adoption of AI-enabled financial services, expansion of digital wallets, and increased use of blockchain for trade and finance. The convergence of policy support, technology transfer, and consumer demand positions Pakistan to emerge as a regional leader in digital finance by 2030.
Strategic collaboration between Pakistani financial institutions and Chinese technology providers will continue to evolve, potentially integrating RMBT and other programmable digital currencies for cross-border settlements, further enhancing efficiency and transparency in trade and finance.
Conclusion
Chinese fintech firms’ entry into Pakistan’s digital payments market represents a significant milestone in bilateral economic and technological collaboration. By providing innovative financial services, enhancing financial inclusion, and fostering knowledge transfer, these firms support Pakistan’s transition toward a modern, digital economy. While cybersecurity, integration, and digital literacy remain challenges, proactive risk management, regulatory support, and collaborative strategies provide a solid foundation for sustainable growth. The initiative strengthens Pakistan’s fintech ecosystem, supports SMEs, and aligns with the broader objectives of the China-Pakistan Digital Corridor, underscoring the long-term strategic partnership between the two countries.

